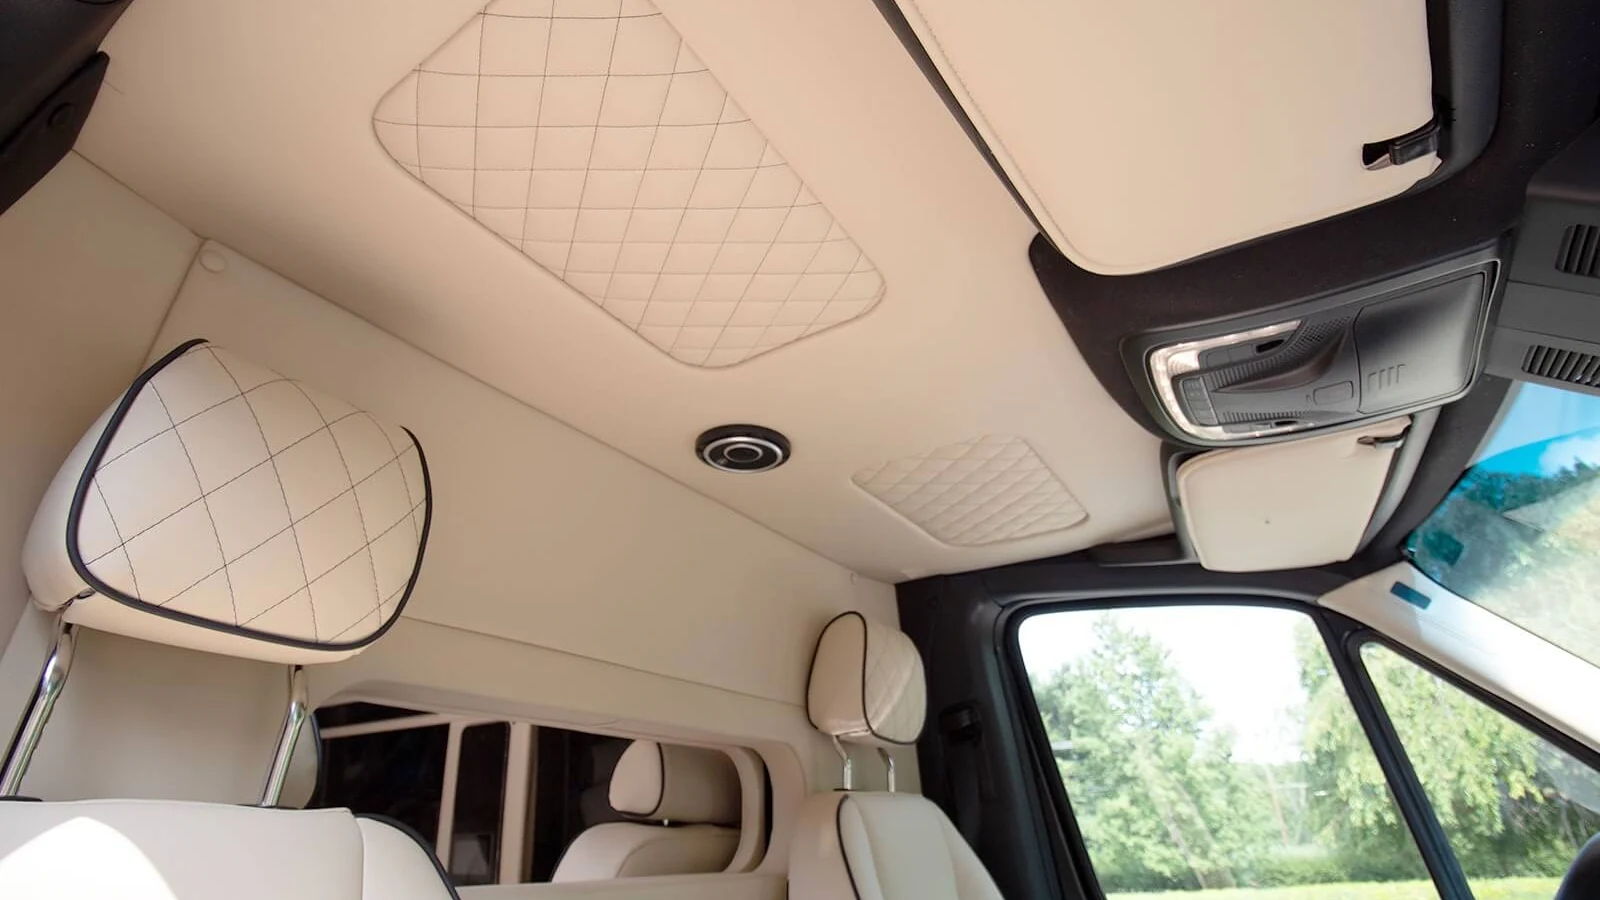
Dufourfun-owned listing photograph of a cream luxury-van cabin. Shown for illustration only; no lender approval or financing is implied. © Dufourfun Vans.
A $150,000 luxury van is a big purchase, and the monthly payment is the number everyone asks about first. It is also the easiest number to make look good by stretching the term. This guide walks through what to compare instead.
Editorial disclaimer: this is general buyer education, not financial, tax or legal advice. Dufourfun does not promise financing availability, approval, rates, terms or tax treatment.
Start with the price, in writing
Before talking payments, get the out-the-door price. The FTC's guidance on dealer ads and promotions recommends getting that price in writing before you go, and suggests getting preapproved for a loan before working with a dealer's financing office. The FTC's financing or leasing a car guide covers the basics of how vehicle financing works.
Compare the whole offer
The CFPB says to look beyond the monthly payment and compare APR, loan term, total of payments and total cost. Its auto loan worksheet is a useful way to line offers up side by side.
Use a table like this for each offer. Fill it in from the lender's written terms; we have left it blank on purpose rather than invent numbers.
| Field | Offer A | Offer B | Offer C |
|---|---|---|---|
| Out-the-door price | |||
| Down payment | |||
| Amount financed | |||
| APR | |||
| Term (months) | |||
| Monthly payment | |||
| Total of payments | |||
| Balloon or residual | |||
| Prepayment penalty |
Shop more than one lender
The CFPB recommends comparing lenders and explains that multiple auto-loan inquiries made within about 14 to 45 days generally count as a single inquiry, though scoring models vary. Offers differ because lenders weigh factors such as credit history, income and debts, down payment, loan amount and term, and the vehicle itself.
Converted vans can be classified differently
A luxury conversion may be viewed differently by different lenders depending on its title, model, intended use and the borrower. One lender might treat it like a passenger vehicle while another asks more questions. Do not assume any specific van qualifies for auto, RV, commercial or equipment financing; ask each lender directly and give them the VIN and build documentation.
Read the fine print
Ask whether the contract has a prepayment penalty. The CFPB explains how to check whether you can prepay without penalty. Before signing, review the Truth in Lending disclosure, which shows the APR, finance charge, amount financed and total of payments.
If the van is for business use
Business buyers should talk with a qualified tax adviser and their lender about their own circumstances. Ask the lender whether a personal guarantee is required for business borrowing. We do not make tax-deduction claims.
Buyer checklist
- Written out-the-door price
- VIN
- Title and body classification
- Chassis and conversion build sheets
- Insurance quote for the exact van
- Loan disclosure from every lender
- Total cost, not just the payment
- Any balloon or residual payment
- Prepayment penalty terms
- Personal guarantee requirements if borrowing through a business
- What happens, and in what order, with funds, title and delivery
Real inventory examples
As purchase examples only, as of October 28, 2026 our inventory included the 2025/26 Midwest Automotive Designs van with Maybach and air-ride upgrades and partition listed at $159,900 and available, and the 2024 Ultimate Toys Limo (coming soon) listed at $149,900. Prices and status can change. Listing a van here is not an offer of financing.
Compare the vans first, then compare the loans.
Find the van that fits your plans
View Vans for Sale to compare available luxury passenger vans. Prefer a layout tailored to the way you travel? Build Your Custom Van.